TSMC stock climbed to another record as investors bet Apple, Nvidia and other chip designers will keep its advanced factories full for years.
The stock rose to NT$2,580, up 3.2%, pushing TSMC’s market value to NT$66.9 trillion.
The rally came as reports suggested major customers have raised 2-nanometre orders by 10% to 20%, forcing TSMC to accelerate capacity expansion.
The shortage is good for pricing, but meeting those orders will require heavy spending as the company ramps up costly 2nm production and overseas fabs.
Nvidia and Apple are pulling the 2nm ramp forward
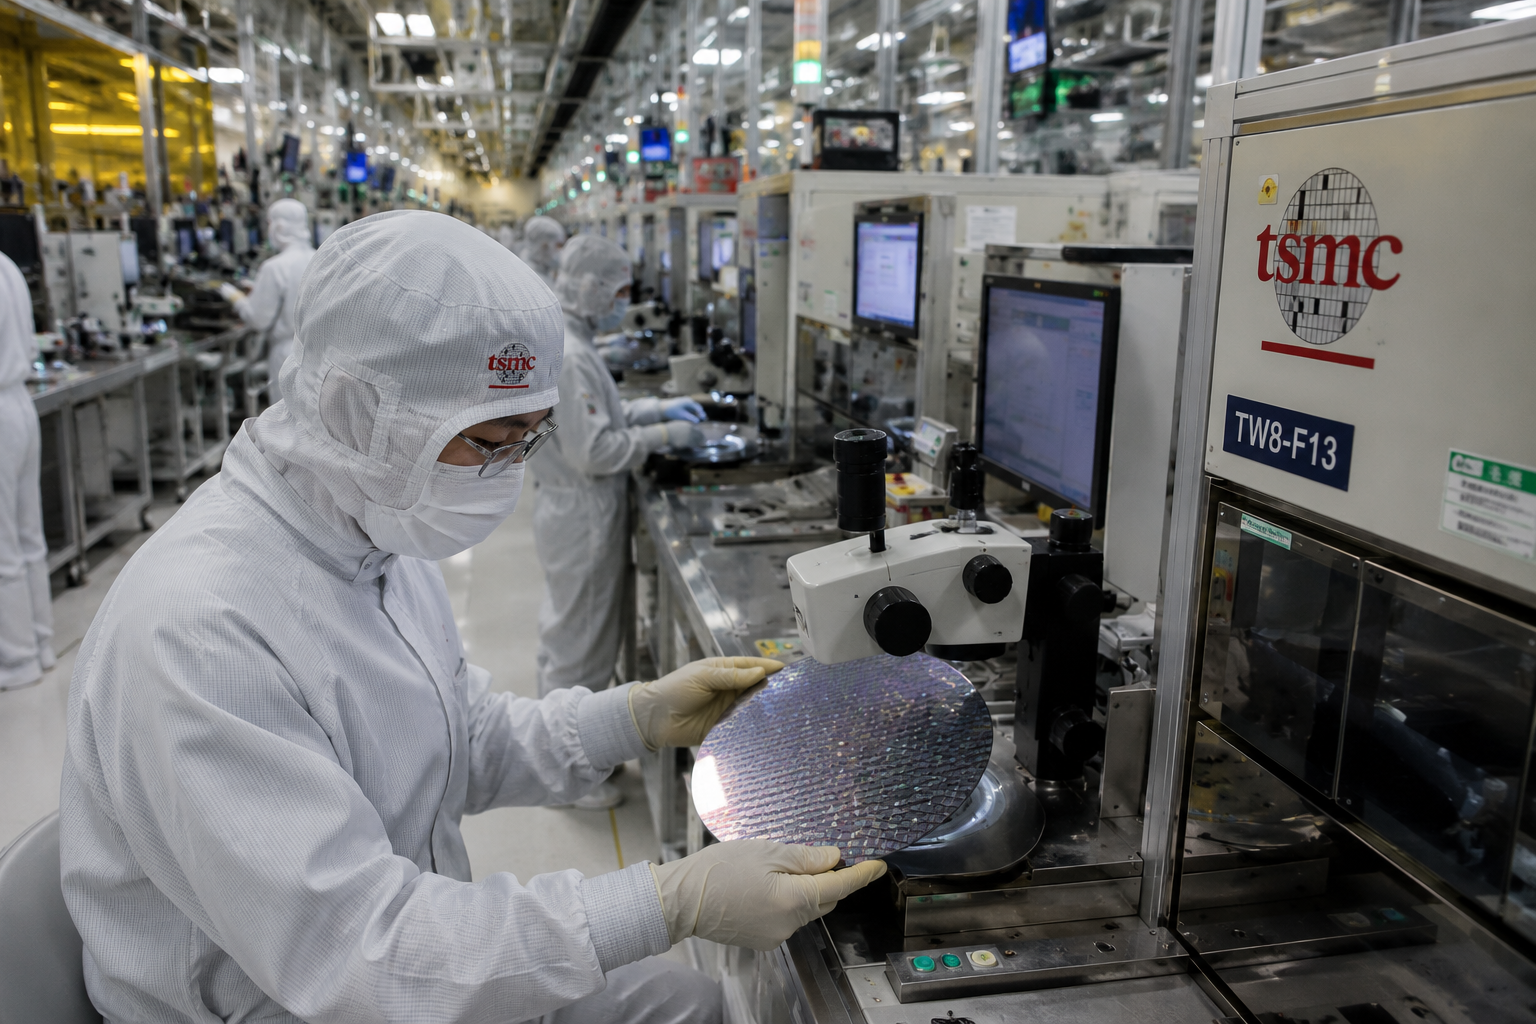
TSMC could reach roughly 120,000 2nm wafers per month by the end of 2026, above earlier estimates of 90,000 to 100,000, according to EDN.
Apple, Nvidia, AMD, Qualcomm and MediaTek have reportedly increased orders for TSMC’s 2nm family by 10% to 20%. The company is bringing five 2nm fabs online this year, including two in Hsinchu and three in Kaohsiung.
TSMC has said first-year 2nm output should be 45% higher than the first year of 3nm, while capacity could grow at a roughly 70% annual rate between 2026 and 2028.
Wall Street remains confident. JPMorgan maintained a Buy rating on October 1 and raised its Taiwan-listed price target to NT$3,300 from NT$3,200.
The message is straightforward. TSMC is not struggling to find customers. Customers are competing for scarce leading-edge capacity.
Too much demand can become an execution problem
The challenge is expanding quickly enough to satisfy demand without damaging the economics of the business.
During TSMC’s July earnings call, JPMorgan managing director Gokul Hariharan said that having undersupply “for a very long period of time is not really desirable for TSMC.”
Persistent shortages can leave revenue unrealised, frustrate customers and encourage chip designers to look for second sources from Samsung or Intel.
TSMC chief executive C.C. Wei said the supply gap is “very big,” while the company lifted its 2026 capital-spending plan to between $60 billion and $64 billion.
Stifel analyst Sahej Singh framed the investor debate last month.
“The debate, in our view, is not about demand but near-term margin durability,” Singh said, according to StreetInsider.
TSMC expects the 2nm ramp to dilute gross margin by about three to four percentage points in the second half of 2026. Separately, overseas fabrication expansion is expected to reduce margins by two to three points in the early stages, widening to three to four points later.
Stifel analyst Sahej Singh still rates TSMC Buy with a $515 ADR target.
Nvidia and Apple can keep ordering more, but TSMC has to spend first to manufacture those chips.
Scarcity also gives TSMC unusual pricing power
Few manufacturers would complain about too much demand when customers have limited alternatives.
Morningstar expects TSMC to raise prices in 2027 because of higher raw-material costs and tight supply.
It lifted its fair-value estimate to NT$3,440, or $534 per ADR, arguing that elevated hyperscaler spending justifies TSMC’s larger capital-expenditure programme.
TSMC plans foundry price increases of as much as 10% in 2027, partly to offset higher materials, equipment and overseas manufacturing costs.
Scarcity cuts both ways. It raises spending requirements and execution risk, but it also strengthens TSMC’s ability to charge Nvidia, Apple and other customers more.
TSMC is due to report September revenue shortly, followed by third-quarter earnings on October 15. Investors will focus on 2027 capex, 2nm economics, AI demand and pricing.
The post TSMC hits another record but Nvidia and Apple demand may become its next problem appeared first on Invezz
